The audit is over, and the examiner’s report says you owe more.
If you disagree, you don’t have to accept it.
An IRS audit appeal sends your case to the IRS Independent Office of Appeals for a fresh review.
But the clock usually starts on the date printed on your 30-day letter.
Miss it, and your options narrow fast.
At a Glance
An IRS audit appeal lets you challenge proposed audit changes before an independent IRS office, but only if you act within the deadline on your letter.
- You generally have 30 days from the date of the 30-day letter to request an appeal.
- Proposed tax and penalties of $25,000 or less per tax period may qualify for a simpler Small Case Request.
- Ignore the letter and the IRS can issue a notice of deficiency, leaving Tax Court as the main path.
- Collection appeals over levies and liens follow different rules and deadlines.
Who this affects: Individuals and business owners who disagree with IRS audit results or face IRS collection action
Updated: September 2026
What Is an IRS Audit Appeal?
An IRS audit appeal asks the IRS Independent Office of Appeals to review audit changes you disagree with. Appeals is a separate part of the IRS. It is not the examiner who audited you, and it is not that examiner’s supervisor.
John Kelshaw joined the IRS in 1983 and spent nearly 40 years there, first as a revenue agent and later as an instructor. A revenue agent is the IRS auditor who handles in-person examinations. Kelshaw describes Appeals as a separate look at the facts from both sides: what you present, what the agent concluded, and what the records actually show.
How Appeals Handles Audit Cases Under IRS Policy
- Appeals will not raise new issues or reopen issues you already agreed to with the examiner, with limited exceptions.
- Most new cases that are not already in Tax Court need at least one year left on the statute of limitations.
- If you bring new evidence to a case not yet in Tax Court, Appeals may send it back to the examiner to review first.
Appeals officers also weigh what practitioners call the hazards of litigation. That means asking how each side’s position would hold up if a court decided the case. Where the IRS position has weak spots, a settlement on part of the adjustment may be possible.
Nothing about that is automatic.
Appeals is not a stalling tactic, either. It works best when you can point to a specific adjustment, show the records behind it, and explain why the examiner got it wrong.
The 30-Day Letter: Your Deadline to Request an IRS Audit Appeal
When an audit ends without agreement, the IRS sends a letter with the examination report. That report lists every proposed change. The letter also explains your appeal rights and gives you a deadline, which is generally 30 days from the date of the letter.
You have three choices. Agree. Protest. Or do nothing.
Doing nothing is still a choice. It’s usually the most expensive one.
⚠ What Happens If You Miss the 30-Day Window
The IRS can issue a statutory notice of deficiency, often called a 90-day letter. You then have 90 days to petition the U.S. Tax Court, or 150 days if the notice is addressed to you outside the United States. Treat that date as fixed. If it passes, the IRS can assess the tax and move the balance toward collection.
Small Case Request or Formal Written Protest?
How you request the appeal depends on the dollar amount at stake for each tax period.
| Small Case Request | Formal Written Protest | |
|---|---|---|
| Amount in dispute | $25,000 or less in proposed tax and penalty for each tax period | More than $25,000 for any tax period |
| How to file | Form 12203, Request for Appeals Review, or a brief written statement | A detailed written protest following IRS Publication 5 |
| Not available to | Employee plans, exempt organizations, S corporations, and partnerships | Required for these entities |
If even one tax period in your case is over the $25,000 line, plan on a formal protest for every period involved. According to IRS Publication 5, a formal protest should include:
- Your name, address, and a daytime phone number
- A statement that you want to appeal the examination findings
- A copy of the letter showing the proposed changes
- The tax periods involved
- Each item you disagree with, and why
- The facts that support your position on each item
- The law or authority you’re relying on
- A signed penalties-of-perjury statement, or a declaration from your representative if they prepared it
One more timing rule catches people off guard. The assessment statute of limitations is the window the IRS has to assess additional tax. When an audit wraps up close to that deadline, the examiner may ask you to sign Form 872 to extend it. Refusing can mean the case never reaches Appeals and goes straight toward a notice of deficiency.
Serving Taxpayers in All 50 States
Holding a 30-Day Letter You Disagree With?
Badran Tax has helped thousands of taxpayers address serious IRS and state tax matters for over 40 years. Our team of Enrolled Agents, CPAs, Tax Attorneys, and Former IRS Agents will review your situation — at no cost.
Schedule Your Free Tax Consultation
or call toll-free: (855) 223-7268
Should You Appeal? Four Common Scenarios
An appeal makes sense when the disagreement is real and you can document it. Here is how that plays out in situations tax professionals see regularly.
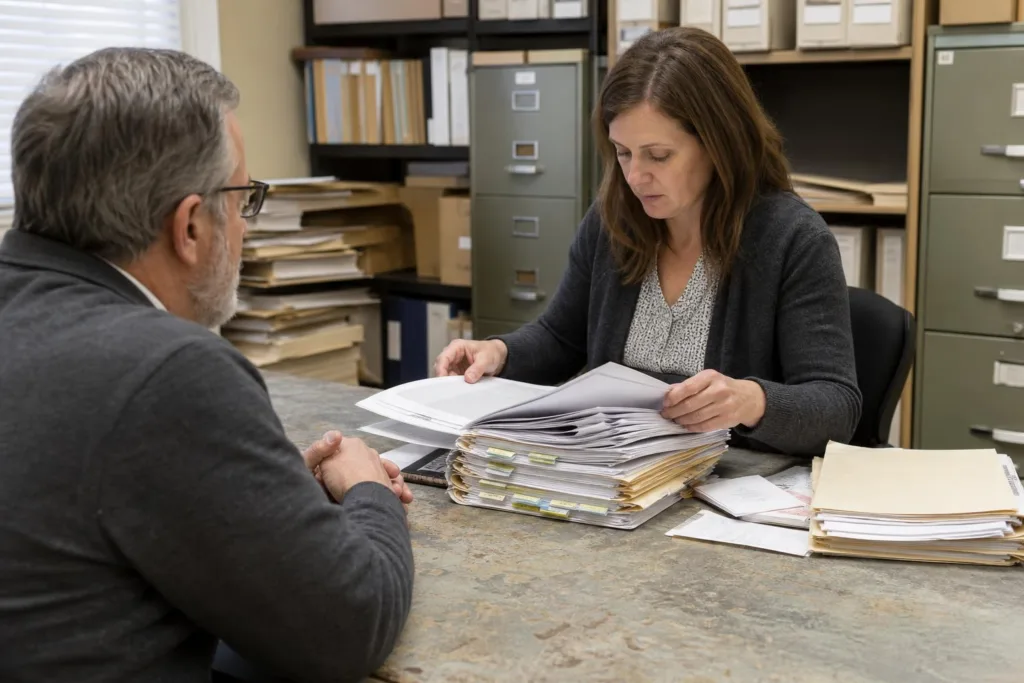
Scenario 1: The Business Owner With Records the Examiner Rejected
The examiner disallowed your vehicle and travel expenses. You have a mileage log, receipts, and calendar entries that line up. The examiner just didn’t find them convincing. This is the kind of case Appeals exists for: a factual dispute backed by paper.
Scenario 2: The Taxpayer Who Disagrees but Has Little Documentation
You’re sure the adjustment is wrong. You just can’t prove it yet. Appeals decides based on the record, so a protest built on frustration rarely moves anyone. Use the 30-day window to rebuild what you can from bank statements, invoices, and third-party records before deciding.
Scenario 3: The Audit That Closed Near the Statute Deadline
Your audit dragged on, and now less than a year remains on the statute of limitations. Appeals generally won’t accept the case in that position. Your realistic choices are signing an extension so Appeals can hear it, or waiting for a notice of deficiency and taking the matter to Tax Court.
Scenario 4: The Taxpayer Who Already Received a 90-Day Letter
The 30-day window is gone. That doesn’t mean Appeals is. If you petition the Tax Court on time and never had an Appeals conference, the IRS generally sends the case to Appeals to explore settlement before trial. Disputes of $50,000 or less per year may qualify for the Tax Court’s simpler small tax case procedure.
How to Prepare an IRS Audit Appeal
Preparation is what separates a protest that gets a real hearing from one that gets filed away. Start the day the letter arrives.
- Circle the deadline. Find the date printed on the letter and count forward. The deadline runs from that date, not from when you opened the envelope.
- Read the report line by line. Separate the adjustments you accept from the ones you dispute. Partial agreement is allowed.
- Match every disputed item to a document. Receipts, contracts, bank records, and logs carry more weight than explanations.
- Choose the right filing. Use the $25,000-per-period test to decide between a Small Case Request and a formal protest.
- Decide how to handle interest. Interest on the proposed balance keeps growing while the appeal is pending. More on that below.
- Send it so you can prove delivery. Use certified mail or another trackable method, and keep a full copy of everything you submit.
Interest Keeps Running While You Wait
The IRS sets no fixed completion date for an appeal. In Kelshaw’s experience, Appeals cases commonly took about 12 months, and he cautions that reduced IRS staffing could stretch that further.
A year of interest adds up. You can stop it on the amount in dispute by paying, or by making a deposit under Internal Revenue Code Section 6603. A deposit is designed for exactly this situation. It stops interest on the deposited amount without conceding that you owe it. Paying outright before a notice of deficiency can change which court can hear your case later, so get advice before you send money.
Do You Need a Representative?
You can represent yourself before Appeals. Attorneys, CPAs, and Enrolled Agents can also represent you once you sign Form 2848, Power of Attorney and Declaration of Representative. Whether that makes sense usually comes down to two things: how much money is at stake, and how technical the dispute is.
The team at Badran Tax helps individuals and businesses respond to audit reports, 30-day letters, and notices of deficiency across all 50 states. If you’re unsure whether your disagreement is strong enough to appeal, a free consultation can clarify where you stand before your deadline passes.
When the Problem Is Collection, Not the Audit
An audit appeal challenges how much you owe. A collection appeal challenges how the IRS collects a balance that has already been assessed. They use different forms, different deadlines, and different rules.
If you’ve received a final notice of intent to levy, the IRS is preparing to take money from your wages or bank account. A levy means your next paycheck may come up short. Here is how the main collection appeal options compare.
| CDP Hearing | Equivalent Hearing | Collection Appeals Program | |
|---|---|---|---|
| Triggered by | Final notice of intent to levy, such as Letter 1058 or LT11, or a Notice of Federal Tax Lien filing, Letter 3172 | The same notices, when the 30-day window was missed | Liens, levies, seizures, and installment agreement denials or terminations |
| Deadline | Within 30 days | Generally within one year | Short and action-specific. See IRS Publication 1660 |
| Form | Form 12153 | Form 12153 | Usually Form 9423 |
| Levy paused while pending | Generally yes | Not necessarily | Depends on the action |
| Tax Court review | Yes | No | No |
A collection hearing is where you can propose a way to resolve the balance. Depending on your finances, you may qualify for an installment agreement, which is a monthly IRS payment plan. Taxpayers in genuine financial hardship may be placed in currently not collectible status, which pauses active collection. Some may be eligible for an offer in compromise, a settlement for less than the full balance when paying in full isn’t realistic.
Appeals will want proof for any of these. Expect to provide current income, expenses, assets, and copies of every notice you’ve received. Showing up without that information leaves the Appeals officer little to work with.
Why the Audit Stage Matters So Much
In a CDP hearing, you generally cannot dispute the underlying tax if you already received a notice of deficiency or had another chance to challenge it. Skip the audit appeal, and you may lose your best opportunity to argue the amount itself.
If a levy or garnishment is already underway, IRS levy and garnishment resolution focuses on stopping the immediate damage while a longer-term solution is worked out.
Frequently Asked Questions
What is an IRS audit appeal?
An IRS audit appeal is a request for the IRS Independent Office of Appeals to review proposed audit changes you disagree with. Appeals operates separately from the examiner who audited you.
How long do I have to file an IRS audit appeal?
Generally 30 days from the date on the letter that offers you appeal rights. Always check the specific deadline printed on your letter.
What is the difference between a 30-day letter and a 90-day letter?
A 30-day letter proposes audit changes and gives you the chance to agree or request an appeal. A 90-day letter is a statutory notice of deficiency, which gives you 90 days to petition the U.S. Tax Court before the IRS can assess the tax.
Can an IRS appeal increase the tax I owe?
Under IRS Appeals policy, Appeals will not raise new issues or reopen issues you already agreed to, with limited exceptions. Interest continues to accrue during the appeal, and new evidence you submit may be sent back to the examiner for review.
Do I have to pay the tax before I appeal?
No. Payment is not required to request an audit appeal. Paying or making a Section 6603 deposit can stop interest from growing on the amount in dispute.
How long does an IRS appeal take?
The IRS does not set a fixed timeline. Former IRS revenue agent John Kelshaw says cases commonly took about 12 months in his experience, and staffing levels can make them take longer.
Can I still go to Appeals after receiving a notice of deficiency?
Often, yes. If you file a timely Tax Court petition and never had an Appeals conference, the IRS generally refers the case to Appeals to try to settle it before trial.
Do I need a lawyer to appeal an IRS audit?
No. You can represent yourself. Attorneys, CPAs, and Enrolled Agents can represent you before Appeals with a signed Form 2848.
What is the difference between an audit appeal and a Collection Due Process hearing?
An audit appeal disputes how much tax you owe. A Collection Due Process hearing addresses how the IRS collects an assessed balance, and it must generally be requested within 30 days of a final levy notice or lien filing notice using Form 12153.
Bottom Line
An IRS audit appeal gives you an independent review of a result you believe is wrong. The window to request one is short, usually 30 days, and missing it pushes the dispute toward a notice of deficiency and Tax Court.
The strongest appeals are specific. They identify each disputed adjustment, attach the records that support it, and arrive on time. If collection has already started, the rules change, and the deadlines tighten again.
If you’re weighing whether to appeal an audit result or respond to an IRS collection notice, Amro Badran, EA, Managing Partner of Badran Tax, and the firm’s licensed tax professionals can help you evaluate your options. With over 40 years of experience resolving IRS and state tax problems, and a team that includes Enrolled Agents, CPAs, Tax Attorneys, and Former IRS Agents, Badran Tax works with taxpayers in all 50 states to identify options and pursue resolution.
40+ Years of IRS & State Tax Resolution
Ready to Resolve Your Tax Problem?
Schedule a free, no-obligation consultation with our licensed tax professionals. We’ll review your situation, explain your options, and help you find a path forward — no matter how complex the issue.
Schedule Your Free Tax Consultation
or call toll-free: (855) 223-7268 | Monday–Friday, 9AM–5PM EST
Sources & Helpful Resources
- IRS: Preparing a Request for Appeals
- IRS Publication 5: Your Appeal Rights and How to Prepare a Protest If You Disagree
- IRS Independent Office of Appeals: AJAC Fact Sheet
- IRS Publication 1660: Collection Appeal Rights
- IRS Form 12153: Request for a Collection Due Process or Equivalent Hearing
- United States Tax Court
Amro Badran, EA, is the Managing Partner of Badran Tax,
With over 40 years of experience and accreditation as a Federal Enrolled Agent,
Amro Badran and his team of tax professionals specialize in helping individuals and businesses resolve complex IRS & state tax issues and controversies.
Experienced and Trusted Tax Resolution Firm based in New Brunswick, NJ.
Disclaimer
This blog post is provided for educational and informational purposes only.
It does not constitute tax, legal, accounting, or financial advice and should not be relied upon as a substitute for professional counseling tailored to your specific situation.
Always consult a qualified tax advisor or legal professional before making decisions based on this content.
Use of this site or information herein does not create a professional relationship between you and BadranTax LLC or its principals. Any reliance on the material is solely at your own risk.
While we strive to provide accurate, up-to-date information, BadranTax makes no warranties, express or implied, regarding accuracy, completeness, or suitability of the content.
Links to external websites are provided for convenience only. BadranTax does not endorse and is not responsible for the content or practices of third-party sites.
BadranTax and its affiliates expressly disclaim all liability for any actions taken or not taken based on this information.